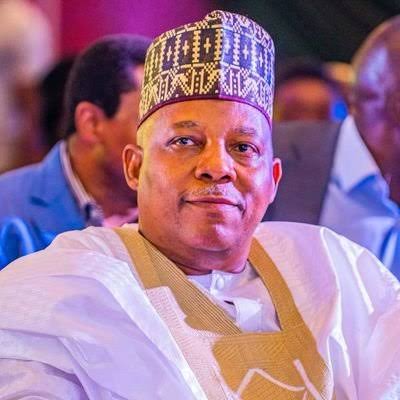

Vice President Kashim Shettima has called for urgent policy reforms, stronger public-private partnerships and innovative risk-sharing mechanisms to attract domestic and foreign investment into Nigeria’s green infrastructure, saying the country requires about 0 billion in additional investment by 2060 to achieve its net-zero pathway
Shettima made the call on Tuesday at the second edition of the Decarbonising Infrastructure in Nigeria (DIN) Summit in Abuja, where policymakers, development finance institutions, private investors, members of the diplomatic corps and climate experts examined ways of closing the huge financing gap confronting Nigeria’s green transition.
Represented by his Deputy Chief of Staff, Senator Ibrahim Hadejia, the Vice President said the scale of funding required presented not only a challenge but also a significant investment opportunity for domestic and international investors.
“Our Energy Transition Plan estimates that Nigeria will require about $410 billion in additional investment above business-as-usual through 2060 to achieve its net-zero pathway.
“That is a significant financing requirement. But it also tells us something else: there is a very large investment opportunity ahead of us,” Shettima said.
He stressed that while government would remain an important player in financing the transition, it could not provide all the capital required to achieve Nigeria’s long-term energy and infrastructure objectives.
“We need the private sector. We need development finance institutions. We need domestic financial institutions and institutional investors. And, perhaps most importantly, we need projects that are properly prepared and capable of attracting that capital,” he said.
The summit, held at the United Nations House in Abuja, was organised by the Office of the Vice President with support from the National Council on Climate Change and the United Nations Industrial Development Organisation (UNIDO).
It was themed, “De-risking Green Infrastructure Investment in Nigeria: Enabling Policy, Project Readiness and Risk-Sharing Solutions.”
Shettima said the central issue was no longer simply the availability of ideas, policies or climate ambitions, but the ability to convert them into projects that investors could assess, finance and implement.
He identified the questions investors would ordinarily ask before committing capital, including whether the policy environment was clear, whether the revenue model was credible, whether technical issues had been adequately addressed and how risks would be allocated among the parties involved.
“These are practical questions. And I believe that is where DIN Summit 2.0 can make a useful contribution,” he said.
The Vice President acknowledged that investment in green infrastructure in Nigeria faced policy, financial, technical and institutional challenges, but said the obstacles could be addressed through collaboration among stakeholders.
He said Nigeria’s NDC 3.0 had recognised the need to develop a stronger pipeline of projects with viable financing propositions, increase private-sector participation and improve access to climate finance.
The Presidency also pointed to developments across Africa aimed at using early-stage project preparation, blended finance and risk-sharing mechanisms to attract private capital into green infrastructure.
It cited the African Development Bank’s Alliance for Green Infrastructure in Africa, which is seeking to mobilise $500 million in early-stage blended finance to help develop a project pipeline capable of catalysing substantially larger investments.
The Personal Assistant to the President on Subnational Infrastructure, Mr Musaddiq Adamu, who welcomed participants on behalf of the DIN Summit Steering Committee, said the summit was designed to answer a practical question: what would it take to move green infrastructure projects from ideas to investment?
Adamu said the DIN initiative had evolved considerably since its first edition, with pre-summit workshops conducted across energy, transport, urban development and agriculture.
He recalled that last year’s summit attracted more than 400 stakeholders and resulted in the launch of the first DIN State Summit Report, while engagements generated between project developers and potential investors had already produced tangible outcomes.
One such outcome, he said, followed a presentation by APM Terminals on the electrification of port operations at last year’s summit.
According to him, the engagement subsequently contributed to a $60 million agreement with the Nigerian Ports Authority to advance port electrification, with Onne Port positioned to become Nigeria’s first green port.
“For me, that is an important lesson. The objective is not simply to have a good conversation. The goal is to create real investment opportunity,” Adamu said.
He said Nigeria had “no shortage of ambition”, with policies, plans and ideas already in place, but stressed that the greater challenge was transforming those ideas into projects that investors could understand, finance and deliver.
Adamu said the ultimate value of the summit would be determined by what happened after the event, urging participants to focus on tangible outcomes rather than discussions alone.
The financing challenge was further highlighted by the UNIDO Sub-Regional Representative in Nigeria and ECOWAS, Ambassador Philbert Abaka Johnson, who said Nigeria’s physical infrastructure investment needs were estimated at approximately $3 trillion by 2050.
Johnson, in his opening remarks, said tracked climate finance flows into Nigeria averaged only $2.5 billion annually in 2021 and 2022, compared with estimated annual requirements of $29.7 billion.
This, he said, left an estimated annual financing gap of about $27.2 billion.
He identified policy and regulatory uncertainty, fragmented approval processes, unclear institutional mandates and undefined revenue or offtake arrangements among the factors preventing otherwise credible projects from attracting financing.
“These projects sit at very different stages of maturity, from concepts which require feasibility work to projects ready to seek finance,” Johnson said.
He said the task before stakeholders was to address the constraints sequentially and ensure that projects were developed to a stage where investors could properly assess their risks and financing prospects.
Johnson said UNIDO remained committed to working with the Federal and state governments and other stakeholders beyond the summit to advance identified project pipelines.
He disclosed that the organisation would deploy its Computer Model for Feasibility Analysis and Reporting (COMFAR) software and Digital Investment Promotion Platform to support project development.
According to him, the tools are already being used by more than 11,000 practitioners across 160 countries.
The UNIDO official said the agency’s support for Nigeria’s industrial transformation was anchored on its Programme for Country Partnership (PCP), 2024-2028, signed in Abuja in April 2025 and valued at approximately $175 million.
He said the programme covered industrial policy and strategic governance, start-ups and enterprise development, special economic zones and industrial parks, agricultural and mineral value chains, sustainable energy and environmental management, as well as trade capacity building under the African Continental Free Trade Area (AfCFTA).
Johnson said the DIN Summit aligned with the sustainable energy, environmental management, special economic zones and industrial parks components of the programme, stressing that Nigeria’s industrial development and infrastructure decarbonisation agenda were closely connected.
He recalled that the inaugural summit brought together more than 400 stakeholders and produced green investment pipelines and a policy communiqué that strengthened coordination among institutions responsible for Nigeria’s infrastructure and climate priorities.
Johnson specifically called for the operationalisation of the Climate Change Act and sanctity of power purchase agreements as part of efforts to unlock carbon finance in Nigeria and across Africa.
The stakeholders argued that improving project preparation would be critical to attracting private capital, particularly for projects that currently remain at the concept or feasibility stage.
The summit therefore sought to establish a more coordinated approach to identifying, preparing and financing green infrastructure projects, while creating mechanisms for sharing risks between government, development finance institutions and private investors.
The Director-General of the National Council on Climate Change, Mrs Tenioye Majekodunmi, who participated virtually, said green infrastructure had the capacity to create more than 300,000 jobs.
The summit also heard calls for standardised public-private partnership agreement templates and dedicated early-stage project development funding to create a pipeline of bankable projects in mini-grids, clean transportation and green buildings.
Participants stressed that investors needed greater certainty around power purchase agreements, revenue structures, regulatory processes and contractual obligations before committing long-term capital to green infrastructure.
With Nigeria’s green transition requiring hundreds of billions of dollars in additional investment, the summit placed project readiness, policy certainty and risk-sharing at the centre of efforts to mobilise private capital and turn the country’s climate ambitions into investable infrastructure.
